
Every station is a make-or-buy decision
A dark software factory is a chain of stations: a request becomes a specification, a coding agent writes the change, tests and a reviewer decide whether it ships, and a record says what happened. For each station, the builder decides whether to buy it (a model call, a hosted agent such as Devin or Factory's Droids, a commodity tool) or to build it in-house.
Agents make that decision live in a way it has not been for decades. A builder can now find a model, brief it, watch it work and dismiss it inside a single request, with a complete log of every instruction it was given. For most of economic history, doing that with a person took a job posting, an interview, a contract and a manager.
The oldest careful answer to make-or-buy is the theory of the firm, and it carries over almost unchanged. The short version, before the theory that gets you there: buy what is generic, build what is specific to you, and keep the right to decide when the specification runs out. That right concentrates in the operator; it does not disappear.
A ninety-year-old question, asked before anyone could type "AI"
In 1937 the economist Ronald Coase published a short paper called "The Nature of the Firm." His question had nothing to do with computers: if prices coordinate a market economy so efficiently, why does a firm exist at all? Why have a little island of command where a boss tells people what to do, instead of everyone negotiating a fresh contract for every task?
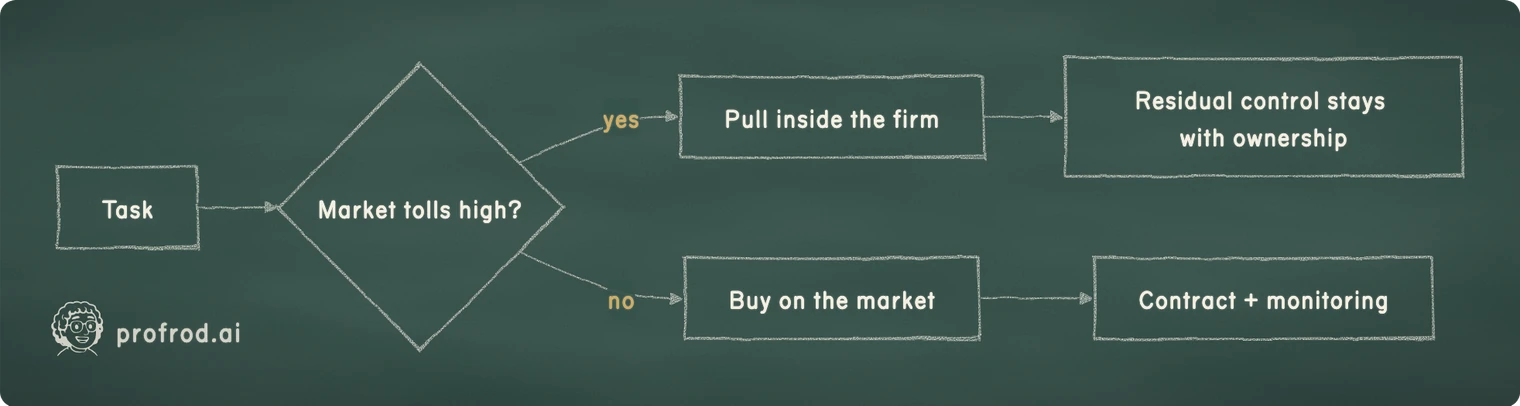
Coase's answer was that using the market is not free. Every time you buy something instead of making it yourself, you pay a toll: finding a supplier, agreeing on a price, writing a contract, watching for someone cutting corners. Bundle enough of those tolls together and it becomes cheaper to hire someone under a standing employment contract, an open-ended agreement to take direction. A firm, in this view, is a cost-minimizing alternative to constant negotiation. It stops growing where running one more task in-house costs more than buying it outside.
You can write that boundary as an inequality. For a task, do it inside when
internal production cost + cost of managing it < market price + transaction costAn agent seems to attack the right-hand side directly. The transaction cost of hiring a model for one task is close to the token price, and monitoring comes with the log. If that were the whole story, the inequality would tip toward the market for almost everything, and firms would dissolve into a cloud of on-demand contracts.
Coase's answer was incomplete on purpose
Coase named the cost of the market. He did not break it down, and economists spent the next four decades doing that. The most useful refinement came from Oliver Williamson, across a 1979 paper and a 1985 book. He argued that whether a task belongs on the market or inside a firm turns on three things happening together:
No contract can specify every future contingency, so every contract is incomplete by construction.
Some investments (a factory built for one customer, a person's firm-specific knowledge) lose most of their value the moment they are redeployed elsewhere.
Given the chance, some counterparties will exploit the gaps an incomplete contract leaves open.
Put those three together and you get the hold-up problem. Once you have sunk a relationship-specific investment, your counterparty can renegotiate the terms in its favor, because you cannot walk away without destroying the value of what you built. Rational parties see this coming and either underinvest or pull the whole transaction inside one firm, where a single authority resolves disputes by decision instead of by fresh negotiation. That is what Williamson says a firm buys: the right to settle an argument by fiat instead of by a court.
A later refinement, from Sanford Grossman and Oliver Hart in 1986 and extended by Hart and John Moore in 1990, asks what bringing a transaction inside a firm actually transfers. Their answer is residual control: the right to decide anything a contract does not cover. Ownership, in this framing, is the specific right to make the call when the paperwork runs out.
For decades the standard illustration of hold-up was General Motors buying Fisher Body outright in 1926, after Fisher allegedly used GM's dependence on its car bodies to charge hold-up prices. In 2000 the Journal of Law and Economics published a set of papers, one by Coase himself, that went back to the archival record. They found a long-term contract and family ownership ties the hold-up story had never accounted for. The theory was not wrong. Its most famous supporting case was. Keep that in mind before trusting any confident story about what agents are doing to firm boundaries, written before the archives on this era exist.
What cheaper coordination touches, and what it does not
An agent attacks the first of Williamson's three legs hard: bounded rationality, in the narrow sense of the cost of communicating instructions and monitoring compliance. It does much less, on its own, about the other two.
| Williamson's leg | What an agent changes | What stays the same |
|---|---|---|
| Bounded rationality | Instructing and monitoring gets close to free | Contracts are still incomplete; the agent still cannot be told everything in advance |
| Asset specificity | Agents themselves are cheap to redeploy | The evaluation sets, context, integrations and tuning built around one agent inside one firm stay specific to it |
| Opportunism | Nothing about software removes the risk of an instruction going wrong at scale | A more capable, more autonomous agent is not a more trustworthy one; it is a more consequential one to get wrong |
Scroll horizontally to view columns.
Cheap coordination does not dissolve hold-up risk. It relocates it, from the supplier contract to the system prompt and the standing permissions an agent was granted once and never revisited.
The middle row is the one a factory builder should dwell on. When every competitor can call the same model and hire the same coding agent, the model is not specific to anyone. What is specific is everything built around it: the cases that define good output for this work, the retrieval index over its documents, the tools wired to its systems, the tests that decide what ships. Those are exactly the assets Williamson says belong inside the firm, and they are where applied-AI and forward-deployed work spends much of its time.
Authority concentrates in the operator
Coase's firm is standing authority instead of repeated market contracts. An operator directing agents by continuous instruction still runs that relation. Membership shrank; authority concentrated.
Much commentary about agents equates "the company has one employee" with "the firm has dissolved." Coase's own definition says otherwise. The firm is the substitution of standing authority for repeated market contracting. An operator directing a fleet of agents, without negotiating a fresh contract for every task, has not dissolved that relation. She has shrunk its human membership to one while keeping the relation intact, and she holds more of it than a management hierarchy ever did.
Residual control makes the point sharper. When an agent meets a situation its specification did not cover, someone has to decide. In a dark factory, that someone is the operator, and so is the liability when the decision is wrong. Who owns the factory's task turns that into a contract the builder cannot silently change, and the review arithmetic works out what it does to the operator's day.
The boundary also does not always move for cost reasons. App-based ride platforms used software to strip out most of the search and monitoring cost that once justified direct employment. California's Dynamex decision in 2018 and the AB5 statute in 2019 pulled that work back toward employment by law, and the Proposition 22 ballot measure in 2020 carved app-based drivers back out again. Make or buy is a legal and political question as much as an economic one.
What an interviewer would ask
A question an applied-AI or forward-deployed interviewer could fairly put to you: a customer wants to know which stations of their agent factory to build and which to buy. How do you decide? Try an answer before opening the one below.
A research-minded follow-up: how would you test the concentration claim?
What this essay is not claiming
None of the above is new theory. Coase, Williamson, and Grossman, Hart and Moore did the work, across five decades, well before anyone trained a language model. What is new is the case in front of the theory: labor that can be procured, instructed and released at a speed and price the classic literature never had to model. zeo, the factory this site runs on, applies these ideas to work beyond software; that names the case, and does not claim the ideas underneath. The organizational side of the question lives at Zero Employee.
The same caution the Fisher Body story raises applies to this essay's own verdict. "Concentrates, not dissolves" is an argument from the theory's logic, not a finding from data about this era. The GM archives are the reminder to keep those two kinds of claim apart.
What would prove this wrong
If factories that adopt agents widely end up buying the assets this essay says they must build (evaluation sets, specifications, context, approval authority) without suffering hold-up, then asset specificity matters less than the theory predicts, and the market end of the boundary is winning. If decision authority in agent-heavy factories spreads out instead of concentrating, the reframe is wrong. Both are observable, given time.
Residual control in practice: bind an agent's authority to an exact proposal, and decide when a human must approve.


